Smallhandy
Small market this week have been better last week. In south east asia – far east route, 10,000 tapico pellets ex ksc – s. Korea has seen low 20s. Beside, 8,000 steel scrap japan to phu my and 6,000 ferts Zhangjiagang – Indo freight aiming 40 to mid 40s, 10,000 calona meal ex yangpu to korea just aiming high teens. In South east asia, market is more active. 6,000 urea ex Bintulu to Ksc, chrtrs aiming 20 – very low 20s, but owrns prefer mid – high 20s. 6,000 mt urea Brunei / Kohsichang is fixed at mid 20s. 15,100 mt hbi Labuan / Cigading is fixed at low 20s. 7,000 scrap ex from Thai to Nghi Son frt is exchanged at low 30s. Some others cargo as sugar, cement re aiming around mid – high teens.
Handysize
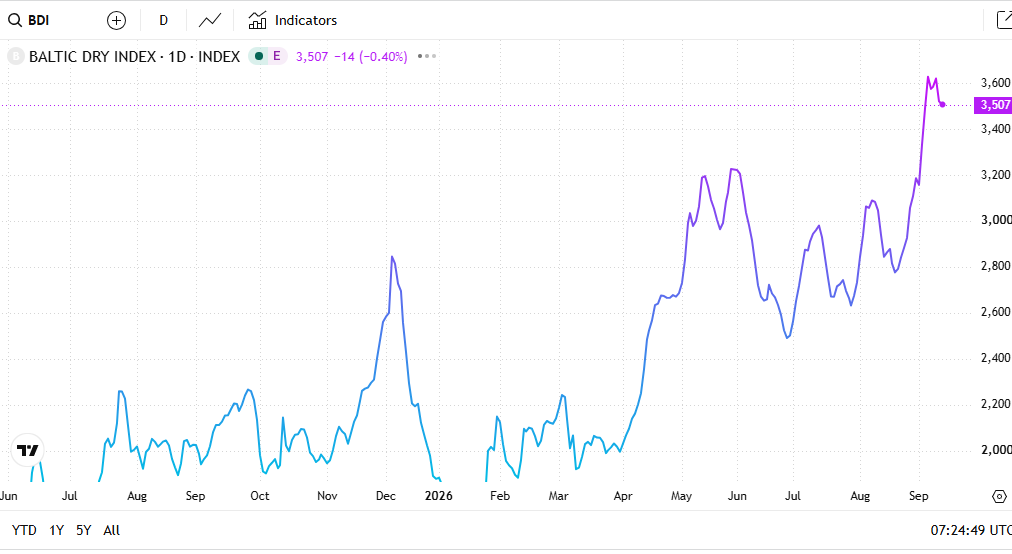
Handysize gained $148 to $16,751, with the Atlantic accounting for the vast majority of the improvement. The US Gulf–Skaw/Passero run was the standout, rising $500 and making the biggest single-route contribution to the index. The Atlantic remained the main driver, while the Pacific had only a limited impact, with its highest-weighted route unchanged. The US Gulf continued to show healthy conditions amid a fairly balanced tonnage list. The Continent and Mediterranean were broadly steady, although fixing activity remained thin, while the South Atlantic moved sideways with a wide gap between owners’ and charterers’ ideas. On the paper side, the overall curve softened across most tenors, with 19 of the 20 listed periods lower and only the far end showing some strength. Atlantic paper was more mixed, with the prompt end firming in line with the stronger physical market.
The Handy market in the South China–Far East region remained fairly stable. A 28,000 DWT vessel was reportedly fixed for an equipment cargo to Oman at around USD 15,000/day.
Supramax
Overall sentiment remained firm, with healthy demand across both basins and good support for modern tonnage. The Pacific continued to lead on longer-haul employment, while the India-Bengal market remained active on Bangladesh and WCI business. With prompt tonnage relatively balanced, owners are expected to remain confident in the near. term.
Pacific The Pacific market remained firm, supported by healthy cargo enquiry and active fixing for both short- and longer-haul employment. Modern Ultramax tonnage continued to attract strong levels, particularly for Med-bound trips via Goa. Reported fixtures included mv Pacific Victory (63.5K/2017) at $24,000 for trip to Med via Goa, while mv Xin Hai Tong 52 (57K/2011) was fixed at around $23,000 on similar direction. In Southeast Asia, mv KM London (63K/2017) was heard fixed at $22,000 for trip via Indonesia to Thailand, and mv Spar Capella (58K/2011) at $20,000 via Indonesia to China. Other fixtures included mv Berge Kaizan (63K/2026) at $22,000 DOP for Indo/Thailand and mv HG Chancay (63K) at $17,000 for Indonesia/China. India-Bengal The India-Bengal market also remained active, with firm demand for Bangladesh and West Coast India employment. Rates were generally well supported, particularly for larger and modern Ultramax tonnage. mv JW Liberty (53K/2005) was heard fixed at $24,000 for trip to Bangladesh with urea, while mv Red Azalea (61K/2015) achieved $21,000 for a coastal trip with redelivery WCI. mv Bahri Ghadah (63K/2019) was fixed at $20,000 via Salalah to WCI. On the East Coast, mv CL Dengsha He (63K/2021) was fixed at around $15,000–15,500 DOP for trip to China with iron ore. Meanwhile, mv Grace Bali (53K/2002) was fixed at $10,000 DOP for trip to Vietnam with gypsum.
Best regards,
