Smallhandy
The small size market exhibited active last week. The idea for South East Asia – Far East route maintains positive rates levels. Dwt 9,000-13,000 is rated at around high 7,000 – low usd 9,000 / day. PKE and Petcoke are exchanged at mid usd 20s – low usd 30s. Dwt 12,000 fixed ferts from Mid China to South Viet Nam at mid USD 30s. For South East Asia route, the rate show a mixed performance. 10,000mt bagged rice ex Yangon to Philippines (2 ports) is indicated at around usd 60s. Dwt 16,000 gless fixed sugar ex Thailand to Phu My at mid teens. 7700mt wbp ex Jakarta to Long An fixed at same level. Urea from Brunei to Philippines is exchanged from low usd 20s to low usd 30s. Besides, 18,000 maize ex Yangon to Philippines – Owners indicate low USD 40s, 6,000mt scrap ex Bacolod to Nghi Son is aimed at high usd20s. For India area, 7,000 PKE ex Sulawesi to Tuticorin is exchanged at low usd 60s. 15,000 mt bag cargo Vizag to Egypt Med – Aiming USD low 70s. Furthermore, dwt 12,000 -13,000 is rated at around 8,000 – 9,000 for period 6 mons to 12 mons trading India – Japan. Small market still keep steady with regular cargo
Handysize
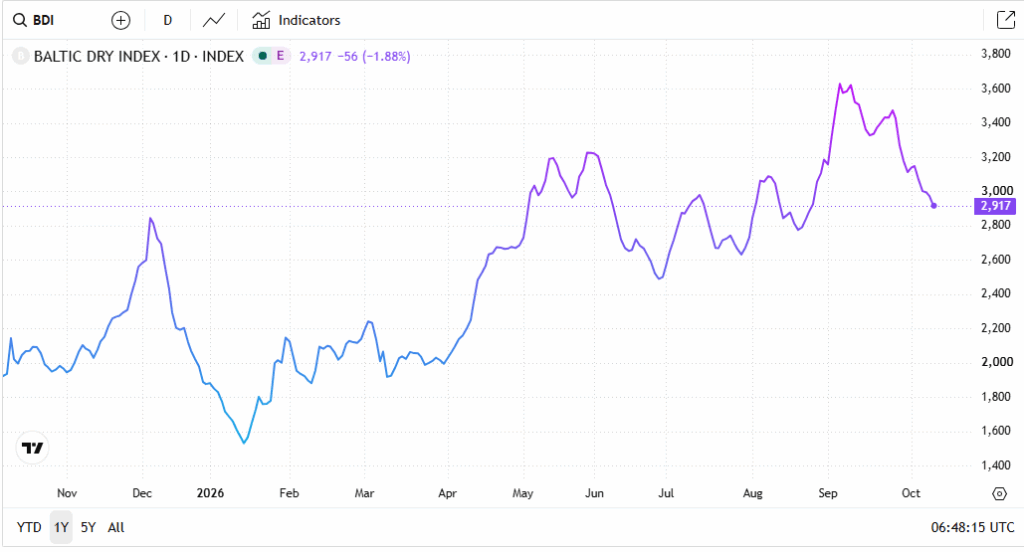
The dry bulk market experienced a mixed trading week, with a sharp correction in the Capesize segment weighing heavily on overall sentiment, while the smaller vessel sectors demonstrated greater resilience. The Baltic Dry Index (BDI) closed at 2,917 points on Friday, 9 October, compared with 3,148 points the previous Friday, representing a weekly decline of approximately 7.3%. The Handysize market showed mixed regional performance throughout the week, with the 7TC average easing to $17,926/day by Friday. Although overall sentiment remained relatively balanced, the contrast between Atlantic regions became more pronounced. Trading conditions remained generally stable, with rates holding close to previously concluded levels. Fresh cargo enquiry was sufficient to maintain market balance, although there was little evidence of a broad-based improvement. A 31,000-dwt vessel reportedly fixed from Casablanca via Morocco to Bangladesh at $18,500/day. The South Atlantic displayed firmer momentum as the week progressed. Healthy cargo enquiry and tightening prompt tonnage availability provided Owners with improved negotiating positions. The region remained one of the more supportive areas for Handysize employment, particularly compared with the US Gulf. The US Gulf continued to soften as limited fresh demand failed to absorb the available tonnage. A relatively long position list encouraged Charterers to maintain cautious rate ideas. A 40,000-dwt vessel reportedly fixed from Upriver to the Continent in the low $30,000s/day, while a 38,000-dwt vessel secured $21,000/day for a wood-pellet shipment from Savannah to the UK-Continent. Asian trading remained relatively quiet due to regional holidays. Nevertheless, rates were broadly stable, with cargo demand and vessel availability remaining reasonably balanced. A 36,000-dwt vessel open Panjin on 7–8 October reportedly fixed for a trip to Southeast Asia at $17,000/day.
Supramax
