Smallhandy
The small-bulk market appears relatively steady to firm, with multiple 6–12k MT cargoes quoted around mid-$20s/mt on regional routes and canola achieving mid-30s/mt, suggesting owners are maintaining freight ideas despite modest parcel sizes. The concentration of fertilizer, fly ash and agricultural cargoes across SE Asia–China/Indonesia/Philippines points to a reasonably active regional handy/small-bulk trade, with rates supported by limited suitable tonnage and positioning requirements, although the narrow spread in indications suggests no major upward momentum yet.
Handysize
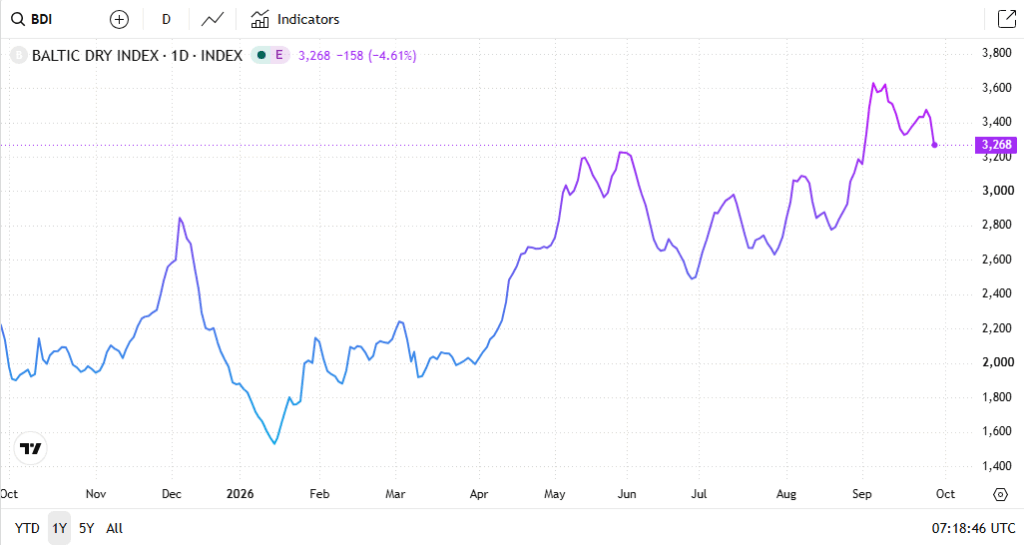
Handysize edged up $30 to $18,061, with the Atlantic once again providing the support while the Pacific softened. The Continent remained the main driver. The Continent–US Gulf route gained $293, exceeding the overall index increase on its own, while the South Atlantic–Continent added $122 and the Continent–River Plate improved by $50. The US Gulf trip, meanwhile, was unchanged. In Asia, the market moved slightly lower. The South East Asia trip slipped $131, while both North Asia routes eased by $8. Reported activity included scrap cargoes fixing at firm levels from both the Continent and Mediterranean, as well as a grain run from Gdansk to the Mediterranean. A 2026-built 43,000 dwt vessel was also reported fixed for a transatlantic trip from Central America at $27,000. No Handysize fixtures appeared on the fixture list. The question is whether the Continent could hold the lead or whether the US Gulf would regain momentum. For now, the answer is clear: the Continent remained firmly in front. The Continent–US Gulf route alone contributed more than the entire index gain, while the US Gulf trip stayed flat. The Pacific finally showed some movement, but in the opposite direction, trimming part of the Atlantic-led advance.
Supramax
The Supramax/Ultramax market remained relatively firm this week, with steady fixing activity reported across both the Pacific and Indian Ocean. Demand for Indonesian coal continued to provide support, while modern and prompt tonnage achieved firm levels. In the Pacific, Mv Ubon Naree (66,029 DWT, built 2026), delivering Dalian on 27 September, was fixed for a trip via NoPac to Chittagong at USD 26,000 per day. Mv BT Trevia (63,581 DWT, built 2016), prompt delivery Bataan, was fixed for a trip via Indonesia back to the Far East with coal at mid-USD 18,000s per day. Mv Vimc Sunrise (56,057 DWT, built 2006), open Singapore, was fixed for a trip via Indonesia to Thailand with coal in the USD 19,000s per day, while Mv Peaceful Seas (63,331 DWT, built 2014), prompt delivery Philippines, was fixed for a trip via Vietnam to West Africa with cement at USD 17,500 per day. In the Indian Ocean and Southeast Asia, Mv Josco Liuzhou (64,231 DWT, built 2022), delivering Haldia in October, was fixed for a trip via Indonesia to India at USD 22,000 per day with coal as the intended cargo. Mv Alexander Schulte (61,579 DWT, built 2019), prompt delivery Gresik, was fixed for a trip via East Kalimantan to Bangladesh with coal at USD 28,000 per day, while Mv Bernina (58,682 DWT, built 2011), delivering Merak on 28 September, was fixed for a trip via Indonesia to Vietnam at USD 22,500 per day with coal as the intended cargo. Overall, reported fixtures indicate that Owners continued to achieve healthy hire levels, particularly for modern tonnage and vessels positioned close to major Indonesian coal loading areas.
Best regards,
